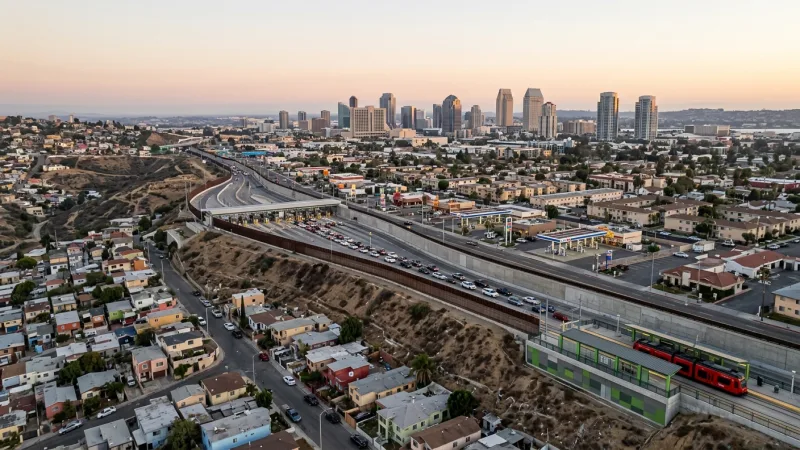
Tijuana is the world capital of the maquiladora. Over 700 IMMEX-certified companies operate in its industrial parks: medical electronics, auto parts, aerospace, textiles, and increasingly digital export services. The world's busiest commercial truck border crossing — Otay and San Ysidro — makes the US supply chain more efficient here than anywhere else in Mexico. What most generalist accountants do not master: Tijuana's border economy blends three tax frameworks that rarely converge in the same business — the state payroll tax before the SHBC, 0% VAT on service exports, and the IMMEX program for manufacturing. An error in any one of them can cost more than twelve months of accounting fees.
Baja California payroll tax: rate, administrator, and the most common installation error
The Baja California payroll tax is 2.5% monthly on compensation paid to workers employed in the state. It is administered by the Baja California State Treasury (SHBC) — independent of the federal SAT. BC's 2.5% rate equals Jalisco's and is one percentage point below Mexico City and Querétaro, but unlike Jalisco — whose ecosystem is primarily tech — the taxable base for a Tijuana company often includes USD-denominated salaries, adding the Banxico exchange rate variable to the monthly calculation.
| State | Payroll tax | Administrator | Filing portal |
|---|---|---|---|
| Mexico City | 3.0% monthly | CDMX Treasury | finanzas.cdmx.gob.mx |
| Jalisco (GDL) | 2.5% monthly | Jalisco Finance | finanzas.jalisco.gob.mx |
| Nuevo León (MTY) | 2.0% monthly | NL Finance | finanzas.nl.gob.mx |
| Querétaro | 3.0% monthly | SHQ | hacienda.queretaro.gob.mx |
| Baja California (TJ) | 2.5% monthly | SHBC | hacienda.bc.gob.mx |
- Federal RFC + updated tax compliance certificate
- SHBC portal (hacienda.bc.gob.mx) → ISN section → new taxpayer registration
- Register the municipality of the establishment (Tijuana, Mexicali, Ensenada, Tecate…)
- Declare whether salaries are paid in MXN, USD, or mixed — SHBC records this
- Obtain BC payroll tax registry number — different from the federal RFC
- If employees also work in San Diego: file only for those physically working in BC
0% VAT on service exports: the most violated rule in Tijuana
Article 29 of the VAT Law is the most relevant tax rule for service businesses in Tijuana — and the most frequently violated. It establishes that services provided to foreign clients whose benefit is used outside Mexico apply a 0% VAT rate. For a Tijuana call center serving San Diego companies, or a design studio billing Los Angeles clients, this means a difference of $160,000 pesos annually in unnecessarily charged VAT per million pesos invoiced — money that raises the service cost against competitors from India or Central America.
| Item | VAT exempt | 0% VAT rate | 16% VAT |
|---|---|---|---|
| VAT charged to client? | No | No | Yes (16%) |
| Supplier VAT creditable? | No | Yes | Yes |
| Generates credit balance? | No | Yes | Only if exceeds payable VAT |
| Applies to exported services | No | Yes (Art. 29 LIVA) | Domestic market only |
| Error if confused with… | 0% → loses credit | Exempt → loses credit balance | Export → unnecessary VAT |
- Client with US fiscal address (generic RFC XEXX010101000 on the CFDI)
- Service benefit used in the US — if part of the service "occurs" in Mexico, that part may be 16%
- Payment received in a Mexican bank account via USD wire transfer, converted at Banxico rate of receipt date
- Supporting documentation: service contract, invoice, bank transfer receipt, Banxico rate confirmation
- CFDI must specify: correct product/service code, issuer's tax regime, RFC XEXX010101000, USD amount, Banxico rate
Banxico exchange rate: the calculation that generates the most errors
In Tijuana it is common for businesses to collect in dollars, pay salaries in dollars, and hold accounts in both currencies. For the SAT and SHBC, however, everything is recorded in Mexican pesos. The correct conversion uses the Banxico published exchange rate for the day of collection or payment — not the bank counter rate, which can differ by up to 3% from the official rate.
Consequences of using the bank rate instead of Banxico: ISR taxable base overstated → excess ISR provisional payment; SHBC payroll tax base miscalculated → incorrect payroll tax; IMSS salary base wrong → incorrect contributions → fine in audit; CFDI with incorrect exchange rate → CFDI invalid for recipient deduction.
IMMEX in Tijuana: the geographic advantage no other Mexican city has
Tijuana hosts the largest number of IMMEX-certified companies in Mexico. The reason is not only industrial — it is geographic. An IMMEX company in Tijuana can import components from San Diego by road on the same day: the distance from a warehouse in Otay Business Park (San Diego) to a plant in Otay Industrial Zone (Tijuana) is 8 kilometers. That physical proximity eliminates import logistics costs and risks that affect plants in Querétaro or San Luis Potosí.
| Factor | IMMEX Tijuana | IMMEX Querétaro | IMMEX Monterrey |
|---|---|---|---|
| Distance to US supplier | 8–50 km by road | 2,200 km (air or ground) | 900 km by road |
| Typical customs crossing | 2–6 hours (Otay/Ysidro) | 1–2 days (Laredo) | 12–24 hours (Laredo) |
| US supplier ecosystem | San Diego, LA, Phoenix | US in general (air) | Texas, Houston |
| Dominant sectors | Medical, electronics, aerospace | Aerospace, automotive | Automotive, steel |
| State payroll tax | 2.5% (SHBC) | 3.0% (SHQ) | 2.0% (SFNL) |
How to choose an accountant in Tijuana for US-facing businesses
| Area | What they must master | Red flag |
|---|---|---|
| SHBC payroll tax | SHBC registration, USD/MXN base filing, annual report | Says "payroll tax is SAT" |
| Export VAT | Art. 29 LIVA, exempt vs 0%, export CFDI | Bills 16% to US clients |
| Exchange rate | Banxico vs bank rate, ISR exchange gain/loss | Uses their bank's rate |
| IMMEX | SE application, inventories, temporary return | Only knows the concept |
| Border REPSE | Shelter companies, US-MX provider verification | Unfamiliar with shelter structure |
- SHBC registration and monthly payroll tax filing
- Correct 0% VAT export CFDI issuance (Art. 29 LIVA)
- Banxico exchange rate calculation for USD payroll and invoices
- IMMEX certification application before the Secretaría de Economía
- REPSE compliance management and provider verification
- Tax planning for US-Mexico binational businesses
Tax calendar for Tijuana companies with US operations
| Obligation | Deadline | Filed with |
|---|---|---|
| Monthly payroll tax (ISN) | 17th of the following month | SHBC Baja California |
| Provisional ISR | 17th of the following month | Federal SAT |
| Monthly VAT (including 0% export) | 17th of the following month | Federal SAT |
| Export CFDI (USD invoice) | Same day as transaction or month-end | SAT (stamping system) |
| IMSS bimonthly contributions | 17th of months 2-4-6-8-10-12 | IMSS |
| INFONAVIT | 17th of each month | INFONAVIT |
| REPSE provider verification | Every 3 months | Internal file + STPS |
| Annual declaration (legal entities) | March 31 | Federal SAT |
| Annual SHBC payroll tax report | February 28 | SHBC Baja California |
| Annual IMMEX report (if applicable) | December–January | Secretaría de Economía |
| Accumulated exchange differences | With annual ISR declaration | Federal SAT |