Accountant in Guanajuato and León 2026: 2% state payroll tax, Bajío automotive cluster and REPSE for manufacturing
27 Oct 2026|20 min read
Kenji Tanaka arrived in Salamanca in 2022 as operations director of a Japanese company supplying Mazda. Seventeen months later, a supplier audit revealed two tax problems his Querétaro firm had not detected: the 2% Guanajuato payroll tax with the SFIN had never been filed — his accountant wrongly assumed the Querétaro payroll tax (3%) where the fiscal address was registered covered workers in Salamanca — and three manufacturing subcontractors delivering partial assemblies had no valid REPSE, leaving his company jointly liable for $1.1 million pesos in unpaid IMSS contributions. Moving the fiscal address from Querétaro (3%) to Guanajuato (2%) also represents a real saving: a company with a monthly payroll of $5 million pesos pays $600,000 pesos less in payroll tax per year in Guanajuato.
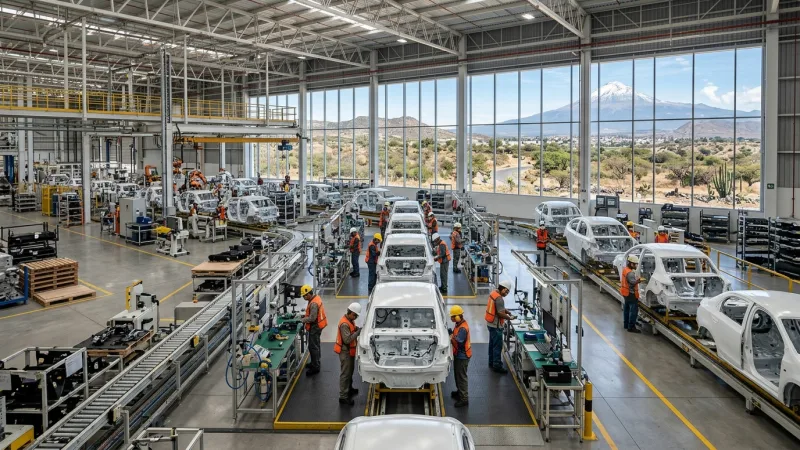
Guanajuato has Mexico's most diversified automotive cluster: Volkswagen in Silao produces the Golf and Tiguan LX; Mazda in Salamanca assembles the CX-5 and Mazda3 for the world market; Honda in Celaya makes the HR-V; GM in Silao produces the Silverado. Alongside the four OEMs, more than 600 Tier-1 and Tier-2 suppliers operate in the industrial parks of Silao, Salamanca, Celaya, Irapuato, and León. This industrial concentration makes Guanajuato Mexico's second-largest manufacturing exporter, with tax obligations ranging from the 2% payroll tax with the SFIN to IMMEX and VAT/IEPS certification for express refunds.
Guanajuato payroll tax: 2% with SFIN — advantage over the Bajío and Mexico City
The Guanajuato payroll tax is 2% monthly, administered by the SFIN at finanzas.guanajuato.gob.mx. It applies to all workers providing services in the state, regardless of where the company's fiscal address is registered.
State
Payroll tax
Administrator
Annual saving vs CDMX*
Mexico City
3.0%
CDMX Treasury
—
Querétaro
3.0%
SHQ
$0
Jalisco
2.5%
Jalisco Finance
$300,000 MXN
Baja California
2.5%
SHBC
$300,000 MXN
Nuevo León
2.0%
SFNL
$600,000 MXN
Yucatán
2.0%
SAF-YUC
$600,000 MXN
Puebla
2.0%
SFA Puebla
$600,000 MXN
Guanajuato
2.0%
SFIN
$600,000 MXN
*Annual saving based on $5 million MXN monthly payroll (average 100 employees, automotive sector).
REPSE in Guanajuato: automotive manufacturing and the special case of León footwear
In Guanajuato's automotive industry, REPSE works similarly to Puebla. But León adds a unique layer of complexity: home manufacturing for footwear. León produces more than 300 million pairs of shoes per year, with a significant portion done by home workshop workers. Since the 2021 reform, SAT has intensified classification of these schemes between legitimate product suppliers and disguised labor subcontracting that requires REPSE.
IMMEX in the Guanajuato Bajío: types and logistical advantage
Guanajuato has a unique logistical advantage: it is equidistant from the three main ports receiving Asian automotive inputs — Manzanillo (Pacific coast, 300 km), Veracruz (Atlantic coast, 420 km), and Lázaro Cárdenas (southern Pacific coast, 280 km). The most common IMMEX certification for foreign companies starting operations in Guanajuato is the Shelter IMMEX: the foreign company does not need to form a Mexican legal entity immediately — it operates under the legal personality of an already-certified shelter company that acts as legal employer and IMMEX permit holder. This reduces startup time from 6-8 months to 4-6 weeks.
Nexoconsult services for companies in Guanajuato and León:
Monthly payroll tax registration and filing with the Guanajuato SFIN
IMMEX management: initial certification, annual renewal, and type changes
REPSE for automotive manufacturing and home manufacturing schemes in León
VAT and IEPS Certification for express refund (5 business days)
Transfer Pricing Study for Japanese, German, and American subsidiaries
Automotive supplier tax calendar in Guanajuato
Obligation
Deadline
Filed with
Monthly Guanajuato payroll tax
17th of the following month
SFIN / finanzas.guanajuato.gob.mx
Monthly VAT
17th of the following month
Federal SAT
Monthly ISR (provisional payment)
17th of the following month
Federal SAT
Monthly IMSS / INFONAVIT
17th of the following month
IMSS / INFONAVIT
Annual ISR declaration
March 31 (legal entities)
Federal SAT
Annual IMMEX renewal
Before expiration
Ministry of Economy
Annual REPSE renewal
Before September 30
STPS / repse.stps.gob.mx
VAT and IEPS Certification (if applicable)
Annual renewal
Federal SAT
Frequently Asked Questions
The Guanajuato payroll tax is 2% monthly on total compensation paid to workers providing services in the state. It is administered by the Guanajuato State Finance, Investment and Administration Secretariat (SFIN) — portal finanzas.guanajuato.gob.mx — independent of the federal SAT and IMSS. The 2% rate is a real competitive advantage versus states like Querétaro (3%) or Mexico City (3%): a company with a monthly payroll of $5 million pesos pays $100,000 MXN in payroll tax in Guanajuato versus $150,000 MXN in Querétaro — a difference of $600,000 pesos per year. This rate difference is one reason the Bajío has attracted manufacturing plants that previously operated in Querétaro or State of Mexico. The most common mistake by automotive suppliers in Guanajuato: having the fiscal address in Querétaro (where they originally registered) but with the plant and workers in Silao, Salamanca, or Celaya. The payroll tax is paid in the state where workers provide services, not where the company's fiscal address is registered. A worker in the Salamanca plant generates Guanajuato payroll tax even if the company's RFC is in Querétaro. The monthly filing deadline is the 17th of the following month.
León concentrates 70% of Mexico's footwear production. The sector has a manufacturing structure that distinguishes it from the automotive industry: a significant part of production is done through "home manufacturing" — workers who perform sewing, cutting, or assembly operations in their own homes, with materials supplied by the company and paid per piece produced. SAT has intensified audits of these schemes because historically many companies paid these workers as "third-party fees" (CFDI invoices as natural persons) avoiding IMSS and payroll taxes, when in reality a disguised labor relationship exists. Since the 2021 outsourcing reform, companies that deliver materials to home workshops and receive specialized work must verify whether those workshops need REPSE. If a workshop worker works exclusively for one company and follows their production specifications, SAT can reclassify the relationship as specialized subcontracting and require REPSE. The difference from automotive: in automotive, subcontractors are typically formal companies with RFC and employees; in footwear, home workshops may be a single natural person with a home workshop, making the boundary between legitimate service purchasing and disguised labor subcontracting harder to define. A specialist accountant in León knows the boundary between a legitimate manufacturing scheme and one SAT can reclassify.
IMMEX allows temporary import without tariffs or VAT of inputs, raw materials, and capital goods to be used in producing goods for export. In the Guanajuato automotive cluster — with VW in Silao, Mazda in Salamanca, Honda in Celaya and GM in Silao — virtually all OEMs have IMMEX certification and require their Tier-1 suppliers to have it as well to operate under consignment supply or cross-border Just in Time schemes. The most common IMMEX types in Guanajuato are: Manufacturing IMMEX (the most common — company imports inputs, produces, and exports), Shelter IMMEX (the foreign company operates under the infrastructure of an already-certified Mexican IMMEX company without immediately forming its own legal entity), and Industrial IMMEX (for industrial services within plants, such as specialized production line maintenance). IMMEX certification requirements in Guanajuato are the same as at the federal level: annual export value of at least USD 500,000; current on SAT obligations; no pending tax credits. Certification takes 30-60 business days with the Ministry of Economy. A common mistake: the Tier-2 company assumes its IMMEX certification is automatically inherited by its sub-suppliers — it is not; each company in the chain needs its own certification if it directly imports foreign-origin inputs.
Compared to a similar supplier in Mexico City, a company supplying Mazda in Salamanca or VW in Silao has three structural tax differences. First — lower payroll tax: 2% in Guanajuato (SFIN) versus 3% in Mexico City (CDMX Treasury). For a medium plant with 200 employees and $6 million monthly payroll: $120,000 MXN payroll tax in GTO versus $180,000 MXN in CDMX — $720,000 pesos annual difference. Second — more accessible IMMEX: Bajío plants have more direct access to the IMMEX program due to proximity to entry ports for Asian inputs (Manzanillo, Veracruz, Lázaro Cárdenas) and Bajío logistics infrastructure (Kansas City Southern rail corridor and MEX-45D highway). Third — VAT and IEPS Certification: since most suppliers in Guanajuato export directly or sell to OEMs that export, qualifying for the VAT and IEPS Certification allows the company to receive VAT refunds in 5 business days (instead of 40 business days for the standard process), significantly improving cash flow. An accountant in Guanajuato with automotive experience actively manages these three differences to maximize the fiscal advantage of the location.
Fees vary significantly by sector and complexity. For a Tier-2 automotive supplier with 50-200 employees in Silao, Salamanca, or Celaya, with primarily local operations (no foreign related parties): between $12,000 and $22,000 MXN monthly for complete accounting, payroll, federal and state tax filings (payroll tax with SFIN), IMSS/INFONAVIT, REPSE compliance, and basic IMMEX management. For a Tier-1 supplier with active IMMEX certification, foreign related parties and need for a Transfer Pricing Study: between $25,000 and $45,000 MXN monthly plus the annual Transfer Pricing Study ($40,000-$80,000 MXN). For a León footwear company with home workshops, mixed payroll, and REPSE management needs: between $8,000 and $18,000 MXN monthly, depending on operations volume and number of subcontracted workshops. A key indicator that the accountant has real Guanajuato experience: they correctly file the payroll tax with SFIN (not another state administration), know the difference between manufacturing and shelter IMMEX for foreign companies in startup phase, and know when a footwear workshop needs REPSE versus when it can invoice as a finished product supplier.